Bitcoin self-custody creates a massive cost-basis blind spot on your 2026 crypto tax forms
The problem — proceeds without basis
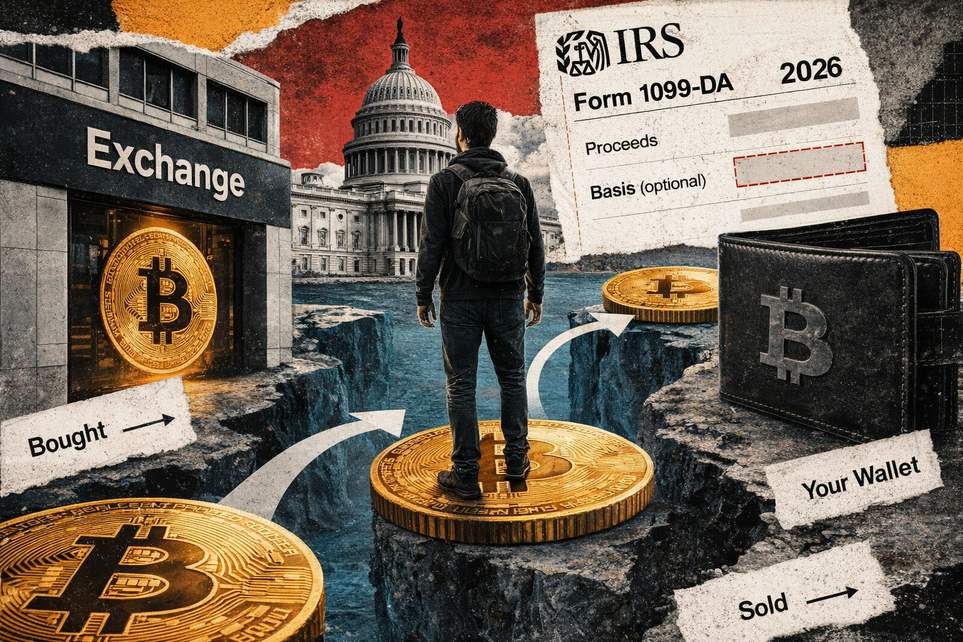
Welcome to Tax Season: The Sequel. For 2026, you might receive a tax form that proudly lists how much you sold your crypto for, but conveniently forgets to tell you what you paid for it. Neat, huh? That’s because the IRS’s new reporting rules treat “covered” digital assets differently: to be considered covered, the asset usually has to be bought after 2025 in a broker’s custody and stay there until you sell it. Move it out, or buy it elsewhere, and the broker may still report sale proceeds while leaving the cost basis blank.
That blank basis box can be terrifying—but don’t panic. A missing basis on a form is not the same as a zero-cost purchase. It just means the broker didn’t (or wasn’t required to) supply the acquisition details. You’re still on the hook to calculate gains correctly using your own records.
Here’s a tiny, drama-free example: imagine you bought 0.1 BTC for $5,000 and later sold it for $7,000. Whether you kept it on the exchange the whole time, bought elsewhere and transferred it in, or withdrew it and sent it back, the economic reality is the same: a $2,000 gain. But the paperwork may look different depending on custody history, and one of those routes can erase the broker’s obligation to report your basis.
Why this happens and what it means for you
The tax rule hinge is “continuous custody at the reporting broker.” If you withdraw coins and then return them to the same account, many platforms treat that returning deposit as a brand-new incoming transfer, not a magically preserved previous purchase. So even when ownership never changed and you didn’t trade in between, the broker can report proceeds without attaching the original acquisition cost.
Transferring coins between your own wallets is generally not a taxable event (unless you accidentally burn a fee-coin that counts as disposal), but the move can break the chain of custody that platforms use to decide what they must report. Platforms may also display estimated gains for your convenience, but what they show you, what they send to the IRS, and what your full transaction history actually supports can be three different things.
Worldwide reporting efforts are rolling out, too. International frameworks and some national tax authorities will start collecting transaction summaries and user data, and blockchain analytics companies are estimating massive volumes of potentially taxable on-chain activity. Those reports can point tax authorities to transactions, but they won’t automatically include the original purchase price, lot choice, or ownership continuity that you need to calculate gains precisely.
Some platforms have begun distinguishing between “proceeds-only” reporting and fuller basis reporting for certain years or assets. Others will calculate internal estimates (like FIFO) for your convenience while still sending only gross proceeds to tax authorities. That means a neat-looking gain on your account screen might not equal the story the IRS ends up with—or the one you have to prove.
The bottom line: more reporting doesn’t necessarily equal complete records. It often equals more pieces of a puzzle—pieces that you still must glue together correctly.
Quick checklist (so your future self doesn’t cry):
• Keep original purchase receipts, timestamps, and transaction IDs. If you moved coins between wallets or exchanges, keep those transfer records too.
• If you plan to use specific identification for lots, identify the units to the broker at the time of sale using their required identifiers—don’t wait until after the fact.
• Don’t assume a blank basis field on a broker form means your cost basis was zero—reconstruct the story from your own files.
• Keep a tidy spreadsheet or use tax software that lets you import wallet/export histories. Reconcile platform displays, IRS-sent forms, and your raw transaction log.
• Watch jurisdictional rules if you live outside the U.S.; international reporting programs may reveal transaction flows without acquisition details.
Tax rules are fiddly, and crypto makes them fiddlier. But you can stay ahead by saving receipts, recording lot choices in real time, and not treating any single platform’s report as the final word. In other words: be boring with records, not boring with your coin picks.
