ARK partners with Securitize to put a venture fund on Ethereum, but leaves exit doors locked
ARK Invest and Securitize just announced a new way for certain investors to hold tokenized shares of the ARK Venture Fund on the Ethereum blockchain. Sounds futuristic? Sure. Useful for getting out fast? Not so much — the fund’s exit rules are still the ones calling the shots.
The short version: ARKVX goes on-chain (sort of)
The tokenized interests represent ownership in the ARK Venture Fund (ARKVX), which continues to hold stakes in a mix of private and public tech companies. Securitize will handle minting the tokens and the on-chain investor experience, but that doesn’t change what the underlying fund actually is: an interval fund with a capped repurchase program.
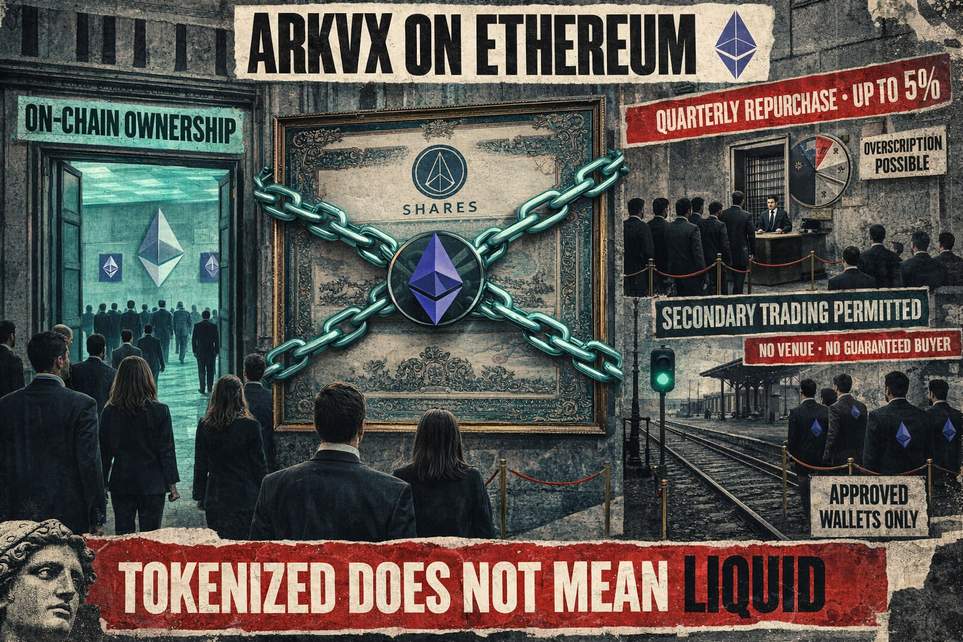
Under the fund’s timetable, there’s a quarterly repurchase window where the fund will buy back up to 5% of outstanding shares at net asset value. That calendar already had a repurchase deadline scheduled shortly after the tokenization announcement, which leaves some uncertainty about whether someone who acquires tokenized interests now can participate in that imminent buyback.
Why this isn’t an instant exit door (investor takeaway)
Don’t expect a bustling secondary market to magically appear the moment a token hits Ethereum. The launch disclosures say the tokenized shares are unlisted and that a lively secondary trading venue isn’t expected at the outset. Regulatory clearance was granted to offer a tokenized share class that could, in the future, trade on alternative trading systems or show up on quotation services — but permission is not the same as liquidity.
The filing puts some real guardrails in place: only approved wallets can hold the tokenized shares, and ARK doesn’t anticipate a robust trading market initially. Mentions of alternative trading systems, over-the-counter deals and peer-to-peer trades are more like theoretical routes than immediate options, and they’d be subject to the controls spelled out in the documents.
Another fine print wrinkle: repurchase offers are allocated across the whole fund, so the tokenized class doesn’t get its own separate buyback pool. Translation: selling via the fund’s repurchase window is possible, but it’s limited and shared with all shareholders.
Bottom line — this is a neat technical move and a step toward modernizing how ownership can be represented, but it’s not a liquidity miracle. If you’re thinking about buying tokenized ARKVX, ask the simple question: will a real market open and attract buyers? Until that answer is yes, the practical way out remains the slow quarterly repurchase process that only takes a small bite of outstanding shares each time.
